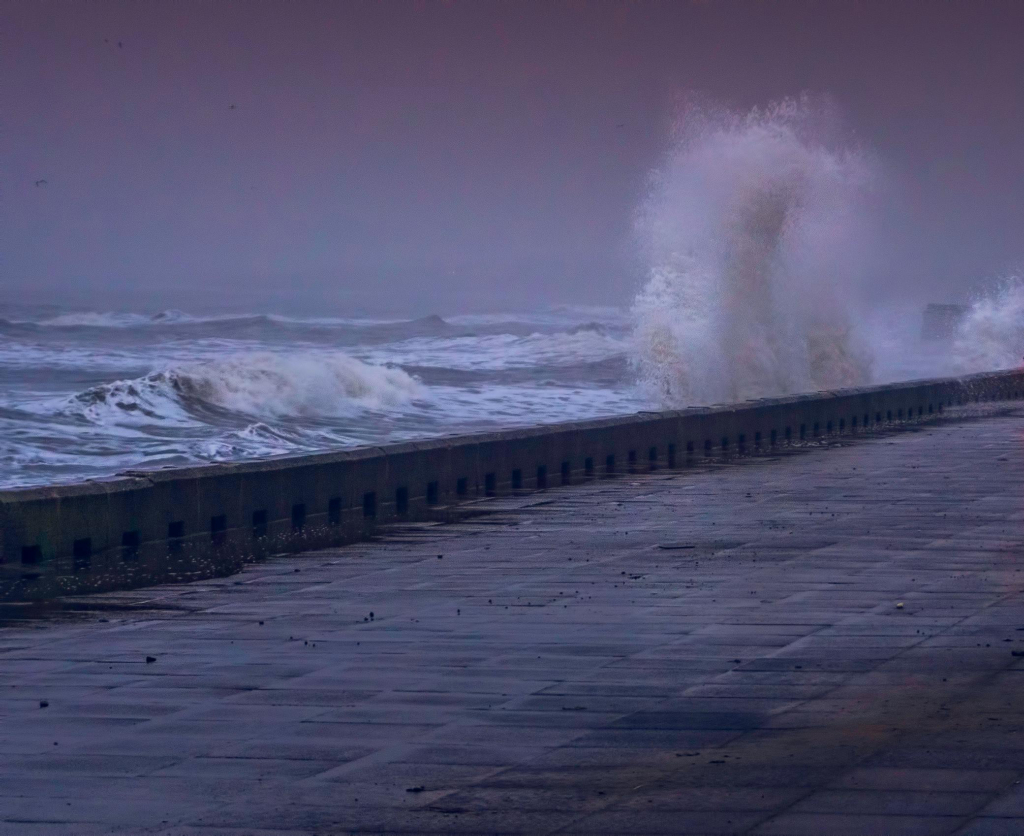
Affected by around 20 tropical cyclones each year, as well as many other natural hazards, the Philippines ranks as the world’s most disaster-prone country. With 7,600 islands and a coastline of 36,300 kilometres, coastal communities are at great risk of storm surges, as Typhoon Haiyan showed in 2013, when more than 6,300 lost their lives.
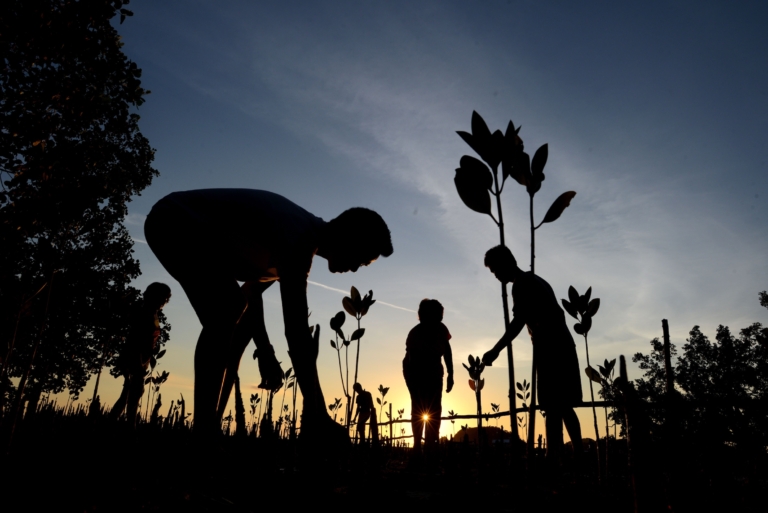
Some of the best protection against that force is already growing along the shore. Mangroves reduce wave height, and with it the impact of storm surges, while also supporting fisheries, sheltering biodiversity and storing carbon. But the Philippines has lost more than half its mangrove forests over the past century, and much of what remains lies outside protected areas.
Philippine Red Cross has long recognised the value of mangroves and invested in afforestation in many parts of the country. However, most humanitarian and disaster risk reduction (DRR) funding comes in short cycles, often annual, while mangroves need at least a decade to deliver their full protective value. Conventional funding is rarely enough to work at the scale and timelines ecosystems need.
The Asia Pacific Nature-Based Risk Reduction & Insurance Facility, led by the Princess Margriet Fund (PMF) of The Netherlands Red Cross, is being designed to close that gap. Its first initiative is a pilot with the Philippine Red Cross, in which a trust fund* combined with insurance cover is intended to protect and restore the mangroves that shelter local communities, and to fund humanitarian assistance when a storm hits. The ambition reaches further: this model could eventually cover more hazards, more ecosystems and more countries across the region.
Ideation and design phase
The facility is in its ideation and design phase, which began in mid-2025 and is expected to run for two years. The Global EbA(Ecosystem-based Adaptation) Fund is funding this phase. HIFHUB provides technical support, the International Federation of Red Cross and Red Crescent Societies (IFRC) provides programmatic support, and PwC Netherlands contributes advisory services for the scale up of the innovative financing components. Allianz Commercial (UK) contributed to the technical insurance design and development during the project’s earlier stages.
“One of the things HIFHUB has brought to the project is the ability to look across the different pieces of the financing model rather than at any one instrument in isolation. As specialist partners have worked on insurance, restoration costs, legal questions and other parts of the concept, HIFHUB has helped us keep asking how those pieces fit together into a coherent and potentially sustainable financing model and how to translate humanitarian priorities into something that insurance partners can engage with. They have helped us navigate a fairly complex landscape of insurers, brokers, legal advisors, and other technical partners, bringing an independent innovative-financing perspective,” said Alex Trowell, Senior Business Development Officer, Princess Margriet Fund.
Nothing is fixed yet, but the current design looks like this:
- The approach is blended finance, where public and private capital are combined: a trust fund would be established, capitalised by catalytic donors* and by the pre-sale of blue carbon credits*. Enabling that pre-sale would mean identifying a large mangrove area that can be protected and that has real protective value for the communities behind it.
- The trust fund would then pay for four things: the one-off set-up, ongoing mangrove maintenance and monitoring, livelihood programmes with local communities, and insurance cover for the mangrove site. Surplus funds would be invested in low-risk instruments such as term deposits and government bonds.
- The insurance itself is envisioned as a hybrid, and both types of cover would pay out to the trust fund, which in turn would fund Philippine Red Cross’s work. Parametric insurance* would pay out fast, covering the humanitarian response and the damage assessment that follows a storm. Indemnity insurance* would then pay for the restoration work that the assessment identifies, because the true cost of repairing a damaged forest is hard to fix in advance.
Early modelling put the trust fund in the low tens of millions of US dollars, with insurance payouts of a similar order when a qualifying typhoon hits. Establishing the exact sizing, both for the fund and for the coverage, is one of the main tasks of the design phase.
Behind all of it is a longer timeline than humanitarian funding usually allows: 25 to 30 years of mangrove protection and restoration.
What comes next
By mid-2027 the team aims to have the insurance concept finished, including the amount of funding needed for the trust fund and the level of insurance coverage required. Alongside that comes identifying the mangrove sites, carrying out various assessments with the communities involved, and preparing to launch the pilot, and laying the groundwork for expanding the model to other countries.
The team has also taken the emerging model into webinars and sector discussions on insurance, carbon finance and humanitarian blended finance, both to test the thinking against other practitioners and to find partners for an eventual regional roll-out. PwC is developing a playbook for what expanding the model regionally would require.
Lessons so far
The model is promising, but it is complex, and the team is building the framework in real-time.
“What has become clear through the project is that there is no single insurance design problem to solve. Insurance, mangrove restoration, site selection and financing are all interconnected. For example, locations with strong carbon finance potential are not always those with the greatest typhoon exposure or strongest case for insurance. Restoration costs, risk exposure and financing assumptions also influence which mechanisms may be viable. Developing a genuinely innovative solution requires testing these assumptions together and adapting the model as evidence emerges,” said Alex Trowell, Senior Business Development Officer, Princess Margriet Fund.
Getting a model like this off the ground takes more than one organisation. The team welcomes conversations with donors, insurers, carbon market specialists and National Societies thinking about similar problems. Get in touch with HIFHUB’s Innovative Finance Advisor Jeremy Tan at johot@rodekors.dk or Princess Margriet Fund, Senior Business Development Officer, Alex Trowell at atrowell@redcross.nl.
To follow how the model develops, subscribe to the HIFHUB newsletter at: https://hifhub.org/newsletter/
About the Asia Pacific Nature-Based Risk Reduction & Insurance Facility
Instrument: a trust fund combined with parametric and indemnity insurance, capitalised by catalytic donors and blue carbon credit pre-sales.
Led by: The Princess Margriet Fund of The Netherlands Red Cross (with Philippine Red Cross as implementing partner on the first pilot project)
Funded by: Global EbA Fund (US$245,727)
Support: HIFHUB (technical), IFRC (programmatic), PwC Netherlands (advisory), Allianz Commercial (UK) (technical, at earlier stages)
Location: Philippines, with regional replication and scale-up envisioned.
Phase: Ideation and design, mid-2025 to mid-2027.
Horizon: 25–30 years.
Terms marked with an asterisk are explained below
Trust fund: a pot of money held and managed separately from any one organisation, so it can hold capital for decades and pay out steadily rather than in short project cycles.
Catalytic donors: often philanthropies, governments, or development institutions providing funds on concessional or risk-tolerant terms to unlock additional investment, typically by absorbing first losses, providing guarantees, or proving a model’s viability.
Blue carbon credits: tradable certificates generated by protecting or restoring coastal ecosystems such as mangroves, which store large amounts of carbon. Pre-selling future credits brings capital forward to where it’s needed now.
Parametric insurance: pays a pre-agreed sum as soon as a defined trigger is met. Because no damage assessment is needed first, money can arrive fast.
Indemnity insurance: conventional cover that pays for damage actually incurred, once it has been assessed and verified. Slower, but it matches the real cost of restoration.